Independent Audit & Assurance Services
Services

Agreed-Upon Procedures

Trust in Us, Confidence in Your Future

General description of the service


The primary purpose of the Service is to perform procedures that have been agreed in advance with the client and provide a “Report of Factual Findings” for each agreed-upon procedure. This report does not provide any assurance as would be provided in an Audit Report or Review Report.

Instead, users of the Report of Factual Findings are responsible for assessing the procedures performed and the findings reported by the auditor, and for drawing their own conclusions based on those findings. The report is used by the client for internal management purposes and is not intended for general external distribution.

Service Usage Context

  • Verification of financial information: Enterprises may use the service when banks, investors or business partners require verification of specific financial information before disbursing financing or making an investment.
  • Support for M&A or business cooperation: In M&A transactions, the buyer may request verification of key financial information rather than a full audit in order to save time and costs.
  • Compliance with contractual or regulatory requirements: Enterprises may need to demonstrate compliance with financial terms under contracts or meet specific requirements imposed by banks, investment funds or regulatory authorities.
  • Support for internal management: Management may proactively request procedures to be performed on specific accounts, transactions or projects to obtain independent verification and additional information to support decision-making.

Service delivery process and timeline


Service process

Service process

  • Work with the client to clearly understand the objectives of the service, for example, verification of receivable and payable balances, revenue, expenses or cash flows.
  • Agree on the specific procedures to be performed, with the scope approved in advance by both parties.
  • Ensure that the selected procedures do not constitute a full audit but instead focus on the specific matters requested by the client.

  • The engagement contract clearly sets out:
    • The purpose of the service.
    • The agreed-upon procedures.
    • The responsibilities of the auditor and the client.
    • The form and content of the report.

  • Identify the data sources and supporting information to be collected, such as accounting records, supporting documents and third-party confirmations.
  • Prepare a detailed work programme for each agreed-upon procedure.

  • The auditor performs the procedures exactly as specified in the engagement contract, for example:
    • Reconcile receivable and payable balances with confirmations from customers or suppliers.
    • Perform physical counts of inventories at warehouses.
    • Reconcile cash inflows and outflows with bank records and supporting documents.
  • Note: The auditor does not express an audit opinion or provide assurance, but only reports the findings resulting from the procedures performed.

  • Record the factual findings observed or identified from the procedures performed, without providing additional interpretation.
  • The report describes only the procedures performed and the findings identified, without expressing an overall conclusion or audit opinion.

  • The report is provided to the client or relevant third parties, such as banks, regulatory authorities or investors.
  • The report is intended solely for the specific purpose agreed upon and does not provide the same level of assurance as a full audit report.

Timeline for Service Delivery

The timeline largely depends on the scope of work, responsiveness, and cooperation of the client (including related third parties such as suppliers, customers, lenders, or investors).

In practice, this service is typically completed within 2 - 4 weeks for most cases. For engagements with urgent deadlines, we implement special measures, such as allocating additional resources, adjusting our workflows flexibly, and requesting proactive collaboration from the client.

thu-vien-ifrs-crowe-vietnam

IFRS library

A collection of in-depth insights on International Financial Reporting Standards (IFRS), developed by Crowe Vietnam’s team of professionals, featuring publications, guidance, and practical information to help businesses stay informed of key developments, strengthen their understanding, and apply IFRS effectively in practice.

Explore the latest IFRS publications and resources from Crowe Vietnam:

Explore more

Quotation process and service fees


Quotation process and service fees

To prepare and send you a tailored quotation, we kindly request that you provide relevant information via our form and/or through an in-depth discussion. Based on the information collected, we will analyze your needs and specific requirements in order to:

  • Assess the feasibility of service delivery: Determine whether we can provide the requested service appropriately and at a guaranteed quality level.
  • Advise on optimal solutions: Recommend alternative solutions (if any) to help optimize efficiency and cost-effectiveness for your organization.

If we are able to support you, we will propose a reasonable fee based on:

  • An estimated workload of the engagement;
  • The level of professional expertise required from our team.

Estimated response time: The quotation process will be completed within 12 to 24 hours upon receiving your request.

Request a Quotation

Frequently asked questions

1. Is my enterprise required to have its financial statements audited?
Whether an audit is mandatory depends on the type of enterprise, its industry and the applicable legal requirements at the relevant time. In addition to statutory requirements, an enterprise may also choose to have its financial statements audited when reliable financial information is required by banks, investors, shareholders, the parent company or business partners.
2. What is the difference between a financial statement audit and a financial statement review?

An audit provides reasonable assurance and includes an audit opinion on whether the financial statements are presented fairly, in all material respects. A review, in contrast, provides limited assurance and generally involves a narrower scope of procedures than an audit. The appropriate engagement depends on legal requirements, the intended use of the financial statements and the needs of relevant stakeholders.
3. What should an enterprise prepare before an audit begins?
Enterprises are generally required to prepare financial statements, accounting books and records, supporting documents relating to material balances, contracts, tax matters, assets, receivables and payables, and significant transactions during the period. A detailed list of required documents will be agreed in advance so that the enterprise can prepare proactively and coordinate efficiently throughout the audit.
4. How long does an audit usually take, and will it affect the enterprise’s operations?
The timeline depends on the size of the enterprise, the complexity of its operations, the quality of its accounting records and the scope of the engagement. Before commencement, Crowe Vietnam will agree the audit plan, timeline and key coordination contacts with the enterprise to minimise disruption to day-to-day operations and ensure the timely issuance of the report.
5. In addition to the audit report, will the enterprise receive recommendations for improvement?
Depending on the scope and findings of the audit, the enterprise may receive discussions or a management letter covering matters identified during the engagement, such as risks, compliance observations, or limitations in processes and internal controls. These insights can help management identify areas for improvement and strengthen the quality of financial governance.

Brand commitment


Crowe Vietnam is committed to building and delivering on its brand personality, with the goal of fostering trust and providing an exceptional experience throughout our journey with clients and partners.

High professional quality at a reasonable cost

High professional quality at a reasonable cost

Crowe Vietnam is committed to delivering high quality solutions and services at reasonable costs, ensuring an exceptional client experience. We consistently strive for differentiation and continuously enhance the professional capabilities of our team to best meet the evolving needs of our clients.

A portrait of our clients & business partners


We aspire to collaborate with clients and partners who are committed to:

Kindness

Being ethical towards clients, employees, and partners through honesty, transparency, and respect for the legitimate interests of all parties.

Legal Compliance

Adhering to all relevant business regulations, including licensing, accounting, taxation, mandatory insurance, labor, goods, and environmental requirements.

Sustainable Development

Balancing profitability with the long-term interests of the community. Building a brand founded on trust and respect from clients and society.

Insights

News

Overview of Crowe Vietnam

Crowe Vietnam Office
Top 9
International brand in Audit, Accounting, Tax, and Business Advisory
Top 9
Audit service provider for FDI enterprises in Vietnam
Top 15
Audit and Advisory service providers in Vietnam
18+
Years of operation (since 2008)
200+
Personnel (350+ including personnel of Crowe’s business associates in Vietnam)
4
Offices
1000+
Clients (1500+ including clients of Crowe’s business associates in Vietnam)

Crowe Vietnam Introduction Video
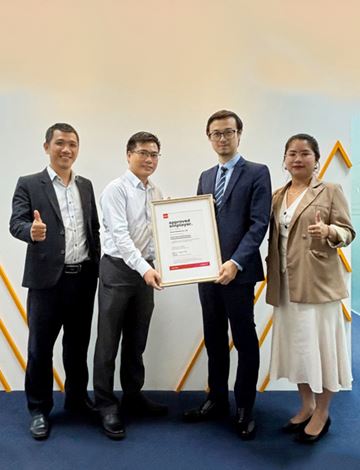
Why choose us for this service?


Choosing the right service partner is a key factor in ensuring both effectiveness and peace of mind. Here’s why Crowe Vietnam is the trusted choice for you.

Senior Personnel

Nam Nguyen
Nam Nguyen
Chairman & Managing PartnerFCPA, CTA, FCCA
Vu Lam
Lam Vu
General Director & Audit DirectorCPA VN, CPA AU, CTA, MA
Tran Tan Phat
Phat Tran
Partner, Audit & AssuranceFCCA, CIA, CPA VN, CTA
Nga Le
Nga Le
Audit Associate PartnerCPA VN, CTA
Dung Nguyen
Dung Nguyen
Audit Associate PartnerCPA AU, CPA VN, CTA
Thuy Phan
Thuy Phan
Audit Associate PartnerCPA VN, CTA
Ngoc Tran
Ngoc Tran
Audit Associate PartnerCMA (U.S.), CPA VN, CTA
Thiem Vu
Thiem Vu
Audit Associate PartnerCPA VN, CTA