UK precision manufacturing
A resilient, capability led sector at the centre of an active M&A market.
| Note: The insights presented in this article are based on publicly available market data, transaction evidence, and industry research available as of September 2026. They should be considered a snapshot of the market and may not reflect subsequent developments. |
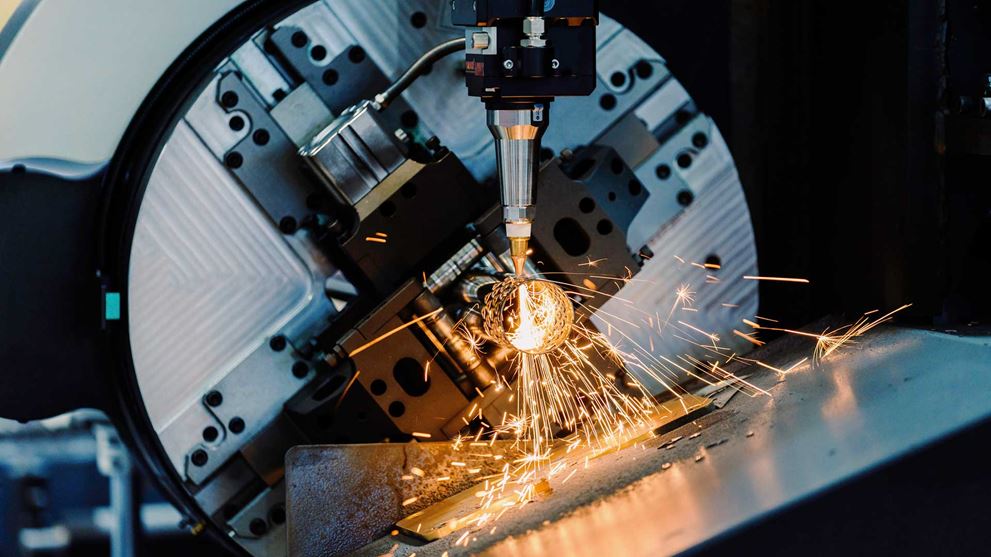
UK precision manufacturing has become one of the most compelling stories in the industrials mid-market. Once viewed as the quiet engineering layer beneath Britain's headline industries, it is now one of the most actively traded and highly sought-after segments of the UK economy. The businesses that machine, fabricate and finish high-tolerance components to exacting specifications sit behind aerospace programmes, medical devices, energy infrastructure, electric vehicles and advanced electronics, and acquirers now recognise them for exactly what they are: strategically vital, hard to replicate, and full of consolidation potential.
The momentum is unmistakable in the deal data. Activity rebounded and strengthened throughout 2025, as both trade acquirers and private equity returned in force, driving consistently high transaction levels across precision engineering and advanced manufacturing, with robust pipelines carrying into 2026 and no sign of a slowdown. 15% of UK private equity deals done in 2026 year to date have been in Manufacturing. (Actum)
Put simply, this is a sector on the front foot, and the businesses within it are being actively pursued by well-funded buyers. The pages that follow set out why investor conviction is so strong, the structural tailwinds powering the sector, and what separates the businesses winning premium outcomes from the rest.
A sector transforming toward higher value
The defining story in UK precision manufacturing is transformation, and it is a story of businesses moving up, not standing still. Over the past five years, the sector has steadily reshaped itself toward higher value, more specialist work, and the businesses that have made that shift are flourishing.
This move toward higher value, specialist production has been most pronounced across CNC machining and injection moulding, driven by aerospace, defence, medical, automotive electrification, and advanced electronics, with customers increasingly prioritising quality, traceability and technical capability over cost alone. The result is that well-invested UK manufacturers with strong accreditations and niche expertise are capturing the most attractive, highest-margin work, insulated from the price competition at the commodity end of the market.
Resilience has been a hallmark of the sector, and a compelling one for investors. Repair and maintenance demand has remained strong, as manufacturers update existing machinery and seek efficiency gains, supporting a healthy flow of bespoke work and helping precision engineers sustain steady profit growth. Businesses with a strong aftermarket and bespoke component position have continued to perform well, demonstrating exactly the durable, cash-generative qualities that acquirers prize.
The picture for an owner is genuinely encouraging. The sector is restructuring toward precisely the kind of high-specification, accredited, capability-led work that commands the strongest demand and the best valuations, and the businesses that have invested to position themselves there are being actively courted.
The structural drivers behind investor appetite
The buyer landscape is deep and competitive, spanning three active groups.
Strategic acquirers
Established engineering groups are pursuing bolt on acquisitions to broaden high-specification capability. Larger players are building integrated, multi discipline platforms combining design, precision machining and complex assembly.
End market expansion
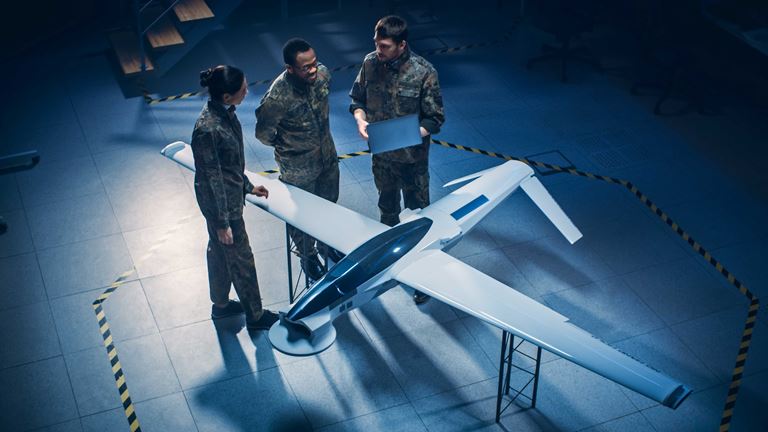
Sector specialists are acquiring to access new end markets such as defence, medical and energy, often driving competitive tension and premium valuations where there is clear strategic fit.
Private equity demand
Private equity remains highly active, attracted by the sector's fragmentation, resilience and consolidation opportunity. This buy and build dynamic is live and visible, with sponsor backed platforms completing multiple acquisitions in quick succession to assemble capability across aerospace, defence, medical, energy and industrial markets.
What drives value in a precision manufacturing business
The evidence on what acquirers reward is consistent and clear. Five factors separate premium outcomes from average ones.
Technical capability and specialisation
Diversified, high-quality end-markets
Scale and platform potential
Profitability and efficiency
Management depth and succession
What this means for owners
For an owner of a precision manufacturing business, the current market presents a genuine and compelling opportunity. Demand for capability is strong, the buyer pool is deep and competitive, valuations for quality businesses are robust, and the structural tailwinds of reshoring, defence, electrification and automation are all working firmly in the sector's favour.
The businesses achieving the strongest outcomes are the best prepared, with a clear demonstration of capability, accreditation, end market diversification, margin quality and management depth. An owner who can articulate the recurring and aftermarket element of their revenue, evidence the longevity of key customer relationships, point to a skilled and stable workforce, and show a management team that does not depend entirely on them, is well placed to command an excellent outcome and to generate real competitive tension among buyers.
For those thinking about acquisition rather than exit, the same fragmentation that is attracting the consolidators is equally available to ambitious management teams. A well-chosen acquisition that adds capability, capacity, accreditation or a new end market can transform both the scale and the strategic positioning of a business ahead of its own eventual exit. In a market moving this quickly, the owners who act with clarity and preparation are the ones who will capture the value on offer.
DisclaimerThis document is produced by Crowe U.K. LLP for general informational purposes and does not constitutes financial advice or a formal offer of services. Market statistics are drawn from publicly available sector deal data and industry research. Sub-sector activity figures and EBITDA multiple ranges are indicative. |
Contact us