Deals Dispatch - UK Technology

M&A update for Q3 2026

Welcome to the Q3 2026 edition of Deals Dispatch, Crowe UK's quarterly review of M&A activity in the UK technology sector.


A challenging M&A environment has continued to impact deal volumes and value in Q3. While total disclosed deal value measured up against previous years, Q3 saw the lowest number of technology sector transactions since the pandemic in 2020. Beneath the headline numbers, however, Private Equity held firm, IT services outperformed software in trade deals for the first time since we started reporting (Q3 2024) and the lower mid-market showed signs of resilience.

For owner-managers, capital remains available and high-quality assets are still commanding strong valuations, but with investment confidence relatively low, buyers are still being selective. Vendor preparation, evidence and timing matter now more than ever.
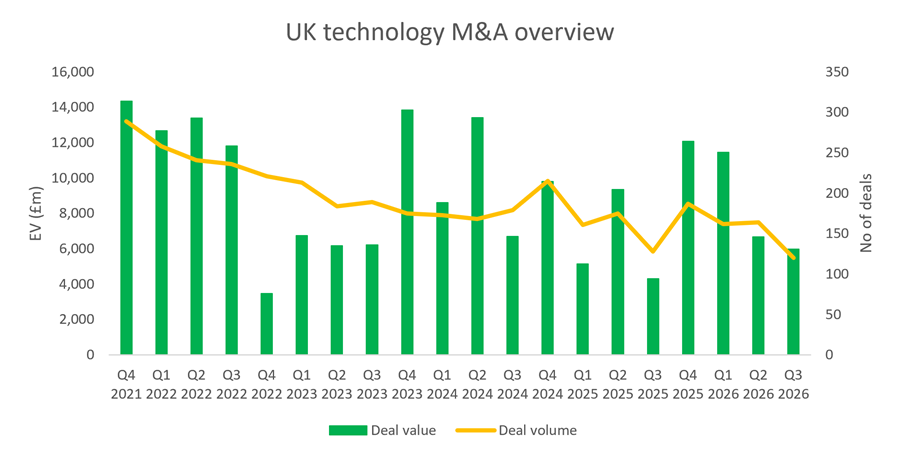
Deals Dispatch Q3 UK technology M&A overview | Crowe UK

Key findings


DEAL ACTIVITY

120

UK transactions completed


MARKET VALUE

£6 billion

disclosed deal value


PRIVATE EQUITY

170% increase

in PE deal volume YoY


PE INVESTMENT

£3.3 billion

PE deal value 

UK SOFTWARE

13x

public UK software EV/EBITDA


UK SERVICES

7.5x

public UK services EV/EBITDA


M&A update for Q3 2026

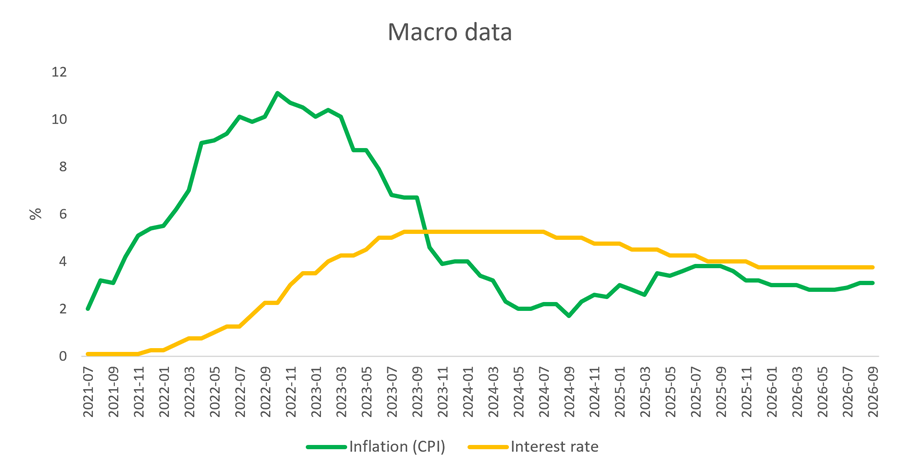
Unfortunately, the macro-economic backdrop failed to improve through Q3. Renewed conflict in the Middle East pushed Brent crude back above USD100 in September and CPI rose to a five-month high of 3.1% in August. The Bank of England held Bank Rate at 3.75%, with three MPC members voting for a rise. An increase to 4.00% has since been implemented.

UK technology M&A slowed to 120 transactions, a 27% reduction on Q2 and 6% year on year, the lowest quarterly total since Q2 2020. Over the last few years we have seen a significant rebound (or catch up) in deal activity in Q4 after relatively quiet summers, so we are hopeful that this trend will continue. Year-to-date deal volumes are only 4% below 2025. Disclosed deal values held up better at £6.0 billion, down 10% on Q2 but up 39% year on year. The mean deal value rose 18% to £69 million on the back of larger transactions such as Softcat’s acquisition of GDT and the Pinewood take-private.

The split between buyer groups was noticeable. Private equity completed 27 deals (worth £3.3 billion), down just 7% on Q2, taking PE’s share of UK technology deals to 23%, the highest in our data. Trade buyers completed 93 deals, down 31% and the lowest since Q2 2020.

Highlights

  • Cyber activity heats up: IBM’s acquisition of Logiq shows how a founder-led specialist can build value quickly with domain expertise and the right strategic focus. Phoenix backed the founders in 2023. Three years and one bolt-on later, IBM are thought to have paid around 23x EBITDA for the business. With Quorum Cyber buying EQT-backed Ontinue for c.£125 million in the same month, cyber remains one of the most sought-after capabilities in the market.
  • Vertical software still earns double-digit revenue multiples: Ridgeview’s £512 million take-private of Pinewood (12.7x revenue) and Hg’s acquisitions of Street Group (12.6x) and Nourish Care (11.0x) each showed the value of mission-critical, regulated workflows that are hard to displace.
  • AI is lifting the UK economy: The IMF has raised its 2026 UK growth forecast by 0.5 percentage points to 1.3%, among the largest upgrades of any major economy, citing AI-related investment and exports. Information and communication output which is the best proxy for the technology sector in the UK is now around 50% above pre-pandemic levels, against around 7% for the economy as a whole. More recently, however, AI-related technology stocks have seen renewed volatility around the US mid-term elections, highlighting how sensitive elevated valuations remain to shifts in political, fiscal and market expectations.

*valuation estimates are from Megabuyte
Observations

  • Trade paused; PE did not: Corporate acquirers who remain exposed to energy costs, slower economic growth and political change have held back on discretionary, strategic M&A. Private equity, while selective, must deploy to survive.  Backed by dry powder and private credit, they have continued to do so. Large strategic deals continue, as IBM and Softcat showed, but growth capital, buy-outs and particularly buy and build platforms continue to create opportunities for vendors.  
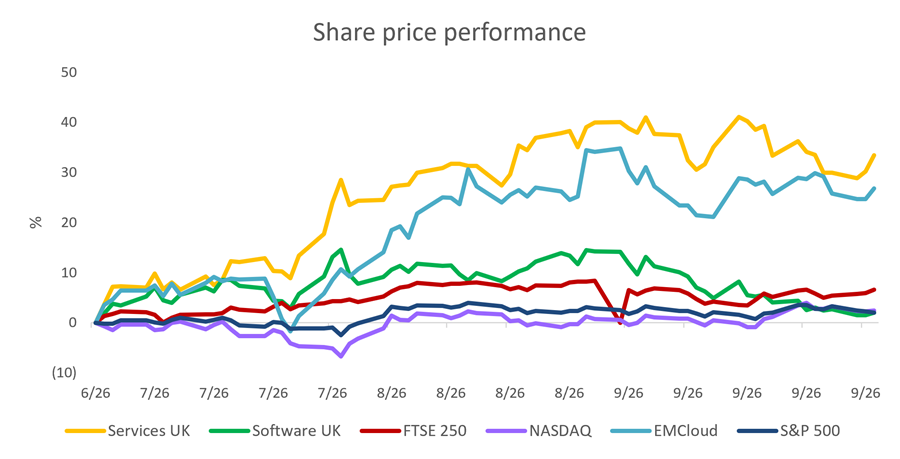
  • Services overtook software, but only the specialists: While marginal, for the first time in our data trade buyers acquired more IT services businesses (47) than software businesses (46). Software deal value fell to £694 million, the lowest in our data. Listed markets told the same story, with UK IT services stocks up around 33% in Q3 against 2% for software. The strength is in specialists; there were just 11 IT managed services deals, the fewest since 2020, while buyers targeted cyber, data, AI enablement and scaled resale.
  • PE exits are flowing, but not for everyone: Half of the quarter’s 16 largest deals had a PE or VC seller. These range from Phoenix’s sale of Logiq to H.I.G.’s sale of GDT, whose EBITDA doubled since its backing in 2021. Further down the market, the picture is more mixed, with many assets acquired at elevated multiples during 2021-22 and now we suspect struggling to attract buyer interest at those same valuations.

Outlook

Deals Dispatch Q3 Macro Data | Crowe UK

While there is still volatility in the technology M&A market, macro-economic conditions have been relatively stable over the last 12 months. The path to lower interest rates now looks longer, however. With inflation forecast to exceed 4% in early 2027, buyers and sellers should plan to use today’s finance costs. Private equity is likely to remain the most reliable source of demand, with corporate activity potentially recovering as the economic and tax picture becomes clearer.

The Autumn Budget on 28 October has set the fiscal framework for M&A activity in 2027. Owner-managers planning a sale in the next 12–24 months should focus on being exit-ready and in particular developing their AI strategy, as this is the key factor driving value creation in technology transactions. We expect a busier Q4 2026 and Q1 2027 as the summer lull unwinds and once the Autumn Budget sets the stage, so owners who are ready to launch early in the New Year may have a competitive advantage in attracting buyer attention.

The market is likely to remain polarised, however. Businesses with proprietary data, embedded workflows and clear evidence that AI strengthens their proposition will continue to achieve strong outcomes. More commoditised providers should expect longer processes, more earn-outs and tighter lender scrutiny.

Spotlight: AI and the IT services business model

In Q2 we looked at why vertical software has proved resilient to AI disruption. This quarter we turn to IT services having seen transactions in this area overtaking software transactions in the quarter. It is also where AI is reshaping the business model most directly.

Trading remains tough. Megabuyte describes the managed services market as “stable but severely subdued”, with organic growth of around 6%, a third of its 2022 peak, and automation progressing more slowly than the hype suggests. However, demand is shifting to specialists in AI enablement, security, data and governance, while business applications work is under pressure. 

Valuations reflect the divide. Subscale, undifferentiated providers struggle to exceed 5–6x EBITDA. Those with £2 million+ EBITDA and 10%+ growth achieve around 7–8x. Scaled specialists can go much higher, as IBM’s 23x EBITDA for Logiq showed.

For owner-managers, the priorities are:
  • focus on where the business has a clear right to win
  • focus on core technologies
  • evidence AI-driven margin gains
  • move towards managed or outcome-based pricing.

Capital markets

Deals Dispatch Q3 Share Price Performance | Crowe UK

Deals Dispatch Q3 Valuation EV/EBITDA | Crowe UK

  • October saw the successful Main Market IPO of Airtel Money, the African fintech business, at a valuation of approximately £5.3 billion. The transaction involved a £529 million secondary share sale and represented London’s largest IPO by market capitalisation since Wise in 2021, providing a welcome boost to UK equity markets following several years of subdued IPO activity.
  • US cloud rallied, UK services led: The Nasdaq was broadly flat in Q3, but the BVP Nasdaq Emerging Cloud index rose around 27% as investors began to see AI as a genuine opportunity for software. In the UK, listed IT services stocks rose around 33% against 2% for software, and the FTSE 250 rose 6.6% to its first record high since 2021.
  • Take-privates are back: Three completed in Q3:      
    • Pinewood: £512 million, around 31x EBITDA
    • Tribal: £231 million, to Main Capital
    • Eleco: £193 million, to Accel-KKR
    • Epiris’s £1.015 billion offer for Gamma should also follow in the next few quarters.
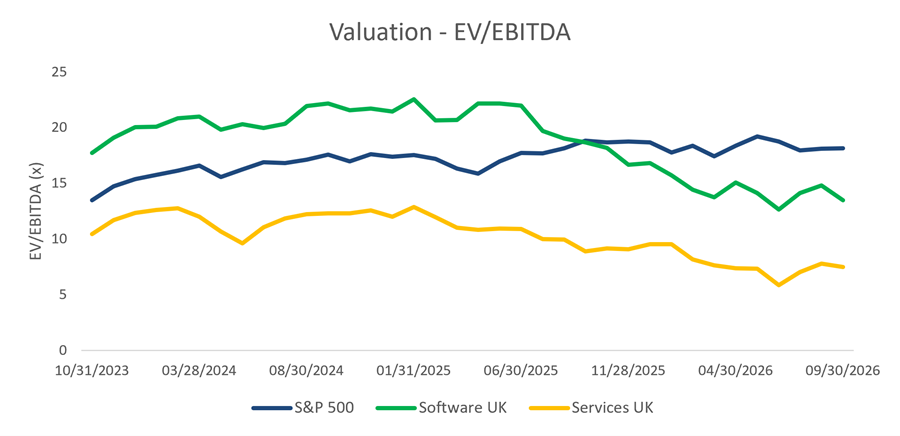
  • Listed UK tech valuations show signs of bottoming out: S&P 500 multiples have held at around 18x EBITDA over the last few years, but UK technology has fallen sharply. UK software has fallen from a peak of around 22x in early 2025 to around 13x, and UK IT services from around 13x to 7–8x. That gap is what is drawing sponsors to listed UK assets, as the return of take-privates shows. Both UK indices have edged up from their summer lows, suggesting we may be near the bottom of multiples.

Lower mid-market

Deals Dispatch Q3 Lower Mid Market Corporate M&A transaction activity | Crowe UK

Deals Dispatch Q3 Lower Mid Market PE Transaction Activity | Crowe UK

*Excludes deals with no reported deal value. 

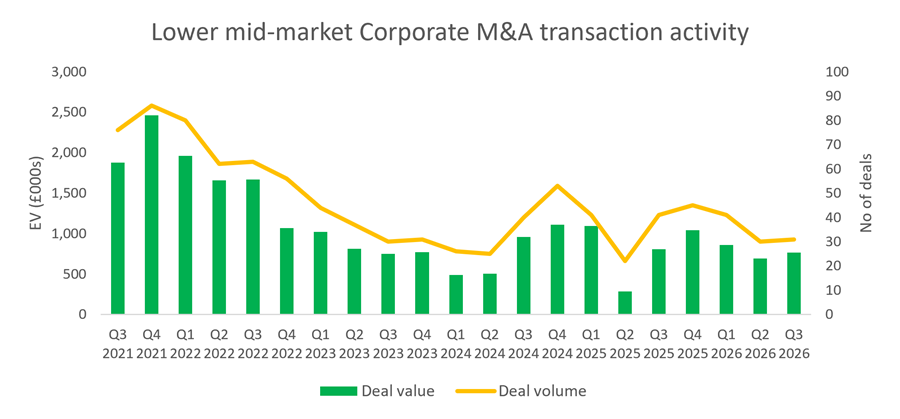
  • Steady while the wider market slowed: 41 deals, flat on Q2 and down 5% year on year, against a 27% fall in the wider market. Value was up 28% year on year to £1.2 billion, and the lower mid-market now accounts for a third of UK technology deals. We suspect that this reflects buy and build activity.
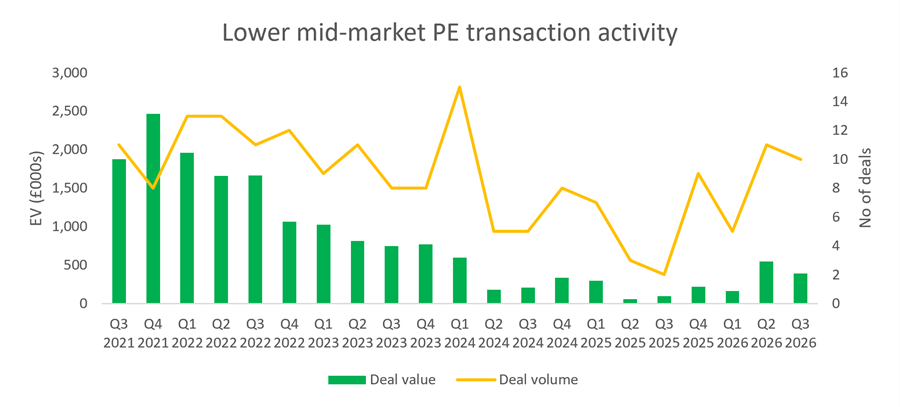
  • PE appetite holding up: 10 PE deals worth £390 million, in line with Q2 and up from just two a year ago. This points to a genuine recovery in sponsor appetite, supported by private credit for buy-and-build activity.
  • Business & Consumer and Telecoms most active sectors: Notable deals in the quarter include FPE’s investment in Business Modelling Applications, Deepki’s acquisition of Camion, Focus Group’s acquisition of Prime Networks and Ask4’s acquisition of IMS Connect

Sources for the article: Bank of England, ONS, Nasdaq, Morningstar, Megabuyte, Takeover Panel, company announcements.

Crowe UK's activity

Q3 2026 transactions we advised

 
Our Corporate Finance team are here to assist you with every step of your M&A journey. Please contact Mark Allen or your usual Crowe UK contact for more information.

Contact us


Mark Allen
Mark Allen
Partner, Corporate Finance 

Related updates