Professional advisor and client in a meeting

Contractual Disclosure Facility and Code of Practice 9

If you're facing a Code of Practice 9 (COP9) investigation or using the Contractual Disclosure Facility (CDF), our team can guide you through the process and help achieve the best possible outcome.

Navigating COP9 investigations, CDF disclosures and undeclared income matters with confidence


A Code of Practice 9 (COP9) investigation or Contractual Disclosure Facility (CDF) disclosure can be complex, time-consuming and highly sensitive. Whether you've received a COP9 offer from HMRC, need advice on making a disclosure, or are concerned about historic tax irregularities, our specialists provide clear, practical support tailored to your circumstances.

Acting on your behalf, our Tax Disputes and Investigations team understands HMRC's civil fraud investigation process and will guide you through every stage, from assessing your position and preparing disclosures to managing communications and negotiations with HMRC on your behalf. Our goal is simple: to protect your interests, minimise disruption and help achieve the best possible outcome.

What is CDF?

Understanding the Contractual Disclosure Facility (CDF)


The Contractual Disclosure Facility (CDF) forms part of HMRC's civil fraud investigation process under Code of Practice 9 (COP9) and is available where HMRC suspects deliberate tax irregularities. In return for making a complete and accurate disclosure, HMRC will generally pursue the matter through its civil investigation process rather than criminal prosecution.

Important: You must seek expert advice immediately if you receive an invitation to use the CDF. There is a strict 60-day deadline to make a valid outline disclosure, or to discuss denial of any wrong-doing and rejection of the CDF.

Accepting the CDF may require HMRC to review up to 20 years of tax history, but it also provides an opportunity to resolve historic tax issues through a civil settlement.

If a COP9 offer is rejected or ignored, HMRC may continue its investigation and consider whether further civil or criminal action is appropriate. Seeking specialist advice at the earliest opportunity can help ensure the right approach is taken from the outset.

The consequences of accepting, rejecting or ignoring a COP9 offer

Accepting a COP9 offer requires taxpayers to disclose all deliberate and non-deliberate inaccuracies in their tax affairs. Provided the disclosure is complete and accurate, HMRC will generally not seek prosecution.

Tax fraud allegations are serious and the conditions of the CDF must be carefully managed. Specialist advice can help ensure deadlines are met, disclosures are comprehensive and communications with HMRC are handled appropriately.

You do not need to wait for HMRC to contact you. In certain circumstances, taxpayers can make a voluntary disclosure through the CDF where protection from prosecution is required in relation to deliberate tax irregularities.

Not every situation is suitable for the CDF. If you believe any tax loss was not deliberate, accepting a COP9 offer may not be the right course of action. In these circumstances, specialist advice is essential to assess your position, determine an appropriate response and manage any subsequent HMRC enquiries.


Add a shield icon or document icon for benefits

risks can be a warning triangle for risks

Benefits of cooperating with the CDF process

  • You will be asked to meet with HMRC at the beginning and end of the process, but HMRC will liaise with your expert advisor in relation to the disclosure report.
  • We can ensure monetary penalties are kept as low as possible.
  • We can help you avoid ‘naming and shaming’.
  • We will ensure the investigation is concluded without delay and that you are treated fairly.
  • All historic matters will be settled by a monetary contract settlement.

Risks of rejecting, ignoring or mishandling a COP9 offer

  • HMRC will take over the investigation.
  • HMRC could seek to prosecute you for not complying with the CDF terms.
  • Third party information notices might be sent to your banks, which could damage to your reputation.
  • Penalties will be higher.
  • You risk being publicly 'named and shamed'.
  • The process will take much longer.

The Contractual Disclosure Facility is complex, but highly beneficial for those potentially facing prosecution.


Co-operation with the CDF process is vital to resolve historic failings without a criminal conviction.

You must seek expert advice immediately if you receive an invitation to use the CDF. There is a strict 60-day deadline to make a valid outline disclosure, or to discuss denial of any wrong-doing and rejection of the CDF.

Admitting there have been deliberate understatements opens up to 20 tax years, but avoids a criminal conviction.

If you reject the CDF offer or if you simply ignore it, HMRC will undertake its own investigation and may build a criminal case with a view to prosecuting you.

The benefits of co-operation and good advice

  • You will be asked to meet with HMRC at the beginning and end of the process, but HMRC will liaise with your expert advisor in relation to the disclosure report.
  • We can ensure monetary penalties are kept as low as possible.
  • We can help you avoid ‘naming and shaming’.
  • We will ensure the investigation is concluded without delay and that you are treated fairly.
  • All historic matters will be settled by a monetary contract settlement.

If you do not co-operate fully and/or receive poor advice

  • HMRC will take over the investigation.
  • HMRC could seek to prosecute you for not complying with the CDF terms.
  • Third party information notices might be sent to your banks, which could damage to your reputation.
  • Penalties will be higher.
  • You risk being publicly 'named and shamed'.
  • The process will take much longer.
  • You will be asked to meet with HMRC at the beginning and end of the process, but HMRC will liaise with your expert advisor in relation to the disclosure report.
  • We can ensure monetary penalties are kept as low as possible.
  • We can help you avoid ‘naming and shaming’.
  • We will ensure the investigation is concluded without delay and that you are treated fairly.
  • All historic matters will be settled by a monetary contract settlement.
  • HMRC will take over the investigation.
  • HMRC could seek to prosecute you for not complying with the CDF terms.
  • Third party information notices might be sent to your banks, which could damage to your reputation.
  • Penalties will be higher.
  • You risk being publicly 'named and shamed'.
  • The process will take much longer.

Under the CDF, you will be asked to make a full disclosure of all deliberate and non-deliberate errors in your tax affairs. HMRC will not seek to prosecute you if you make an accurate and complete disclosure.

Accusations of tax fraud are serious and specialist advice  must be taken to meet the conditions, otherwise you risk prosecution.

You do not need to wait for HMRC to act: you can make a voluntary request to use the CDF if you need protection from prosecution.

If you believe that a loss of tax has not been brought about deliberately, you must not accept the offer of the CDF as a matter of convenience. In these circumstances, you should reject the offer. HMRC will then start its own investigation, reserving the right to pursue a criminal investigation. Although the 'co-operative denial' route is no longer available, we can help you frame your response in such a way that will encourage HMRC to work with us to resolve any perceived issues.

How we have helped our clients


woman writing on glass board in meeting

No resolution

We will work with your current advisor to ensure the best outcomes.
woman showing papers to another person

Voluntary disclosure

We won’t shy away from tough conversations that benefit our clients.
Two men looking at ipad in office

Bespoke Solutions

We tailor our approach to every case, ensuring the best possible outcome.

How we can help

Any tax investigation or disclosure is sensitive and requires careful handling.

The tone of correspondence can be intimidating and dealing with HMRC can be very stressful. However, you will avoid being prosecuted for tax fraud if you meet your obligations under the CDF and make a full and frank disclosure.

Crowe’s experienced and award-winning Tax Disputes and Investigations team can help you navigate the CDF process and ensure you meet your obligations.

We frequently work with other accountants and solicitors to help their clients who are invited to use the CDF and can work alongside existing advisors in a consultancy capacity.

Get in touch


You can email or complete our booking from to arrange a free confidential consultation.

email_24px      forum_24px

Frequently asked questions


What is HMRC COP9 and the Contractual Disclosure Facility (CDF)? 
Insert Content
Why has HMRC sent me a COP9 letter? 
Insert Content
What happens during a COP9 investigation? 
Insert Content
How far back can HMRC investigate unpaid tax? 
Insert Content
Can I make a voluntary disclosure before HMRC contacts me? 
Insert Content
How does HMRC discover undeclared income? 
Insert Content
How is a COP9 investigation different from COP8 and other HMRC investigations? 
Insert Content
What penalties can HMRC charge under COP9? 
Insert Content

Our latest thinking


We're here to help


Anyone with tax irregularities that have been deliberately brought about should seek specialist help as a matter of priority. In these circumstances, the CDF (or Code of Practice 9) is a good place to be, compared to the alternative!

Our experienced and award-winning Tax Disputes and Investigations team can help you navigate the CDF process and ensure you meet your obligations.

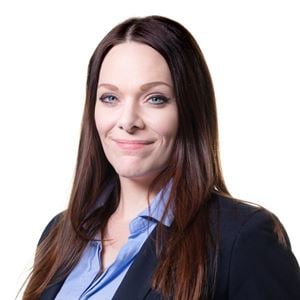
Hayley Ives
Hayley Ives
Partner, Tax Disputes and InvestigationsLondon
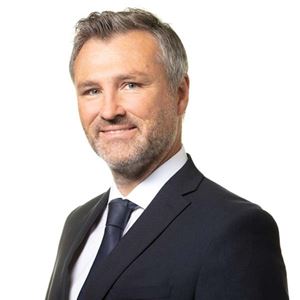
Mark Ayre
Mark Ayre
Director, Tax Disputes and InvestigationsLondon
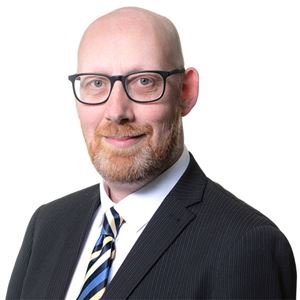
Ian Shirley
Ian Shirley
Director, Tax Disputes and InvestigationsMidlands

Book a free consultation

We are an independent tax advisory firm that helps clients navigate HMRC investigations, disclosures and disputes.

* Complete required field