Inheritance Tax
Could it impact you?
Inheritance tax (IHT) receipts are on the rise and in June 2026, they hit the highest on record. According to HMRC's August 2026 monthly bulletin, IHT receipts for April 2026 to July 2026, they reached £3.2 billion, the highest on record for this period. HMRC tax receipts and National Insurance contributions for the UK (monthly bulletin) - GOV.UK
With frozen allowances, upcoming changes to legislation around pensions and business relief, this upward trend is expected to continue, and a lot of estates are now giving rise to a liability where there was previously none.
The important point to remember here is that we can plan for IHT and there are strategies with varying levels of access, control, cost and complexity, but there are options available to you.
What is it?
IHT may arise on your estate, normally at a rate of 40%, if your estate exceeds the allowances available. How this liability is met can be a source of great stress for executors, especially if a large portion of your wealth is illiquid through assets such as property holdings. It is important that a clear and established plan is communicated intergenerationally to ensure that your legacy is secured.
What is available to you?
The following are the main allowances that can be used to offset against your estate for IHT purposes.
Spousal exemption – if you are married or in a civil partnership, you can pass any asset to your spouse without tax implications, which includes receiving assets on death. There are no cohabitation rights for couples that are unmarried/not civil partners regardless of the length of your relationship so keep this in mind for continuity planning.
Nil rate band (NRB) – there is a nil rate band of £325,000 per person which can be offset against the value of your estate. If your estate is below this value, no IHT will be due.
The caveat to be aware of here is any non-exempt financial gifts you have made will deplete your nil rate band first until they fall outside of your estate after seven years. For example, if you made a non-exempt gift of £50,000, your nil rate band would reduce to £275,000 for the next seven years.
Residence nil rate band (RNRB) – this allowance can be offset against the value of a property that has ever been your main residence value up to the lesser of the total value of the property and £175,000, provided the property is passed to a direct descendant. This includes children, grandchildren, step-children, foster children and children where you have been appointed by a court order as a guardian or special guardian if that appointment took effect when the child was under the age of 18. For clarity, if your house is worth £100,000, you will only benefit from an allowance of £100,000. If it is worth £600,000, you will only benefit from an allowance of £175,000.
If you do not have any direct descendants, your estate cannot benefit from this allowance. If you are cohabiting (i.e. unmarried/not civil partners) and you pass your residual share of your property to your partner on death, again, your estate cannot benefit from this allowance. If your estate exceeds £2 million, then this allowance reduces by £1 for every £2 of estate above £2 million.
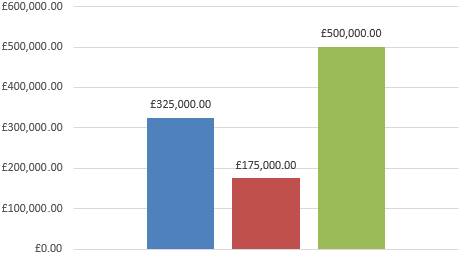
Provided you are eligible for these allowances, this gives you a total of £500,000 to offset against IHT or £1 million per couple if married or in a civil partnership.
Who will IHT impact?
Through both the nil rate band allowance being frozen since 2009/2010 and increasing asset values, particularly in property, and with pensions falling into the estate from April 2027, this is becoming an increasingly common issue.
More and more estates are being caught by IHT through fiscal drag and you may be impacted when you previously haven’t been, potentially putting your legacy at risk.
Summary
There is the view that IHT is unnecessarily complex and contentious, with some estates being able to benefit from an additional allowance if they have children. Although this could promote intergenerational planning, with modern-day family complexities, coupled with a lack of cohabitee rights when passing assets to one another, the rules feel outdated.
Could it be modernised and simplified? Absolutely, but with frozen allowances, those falling into the IHT trap will continue to grow.
This is a planning risk which people often sleepwalk into. There are solutions available to you, but we need time for these strategies to take effect. If you are in doubt and want to secure your legacy, contact us today.
Get in touch
Call, email, sign up for our newsletter, or complete our contact us form to arrange a confidential consultation.


Meet our Crowe Financial Planning team
DisclaimerCrowe Financial Planning UK Limited is authorised and regulated by the Financial Conduct Authority (FCA) to provide independent financial advice (FRN 185323). This insight is approved for use by Crowe Financial Planning UK Limited on the date issued. The information on this page is for information purposes only, based on our understanding of legislation and market practice at the time of writing. It does not constitute financial, legal or tax advice, and appropriate professional advice should be sought before any course of action is pursued. Where professional financial advice is sought, fees will apply and will vary depending on the complexity of the individual case. Any advice will be based on personal circumstances, and as with all financial planning, outcomes will depend on a range of factors that cannot always be predicted or guaranteed. The value of investments can go down as well as up and is not guaranteed; investors may not get back the amount originally invested. Past performance is not a guide to future performance. Tax treatment depends on individual circumstances and is subject to change. The FCA does not regulate Trusts, Tax or Estate Planning. The division of pension assets on divorce involves both financial and legal considerations, independent legal advice should be sought alongside any financial planning guidance. Please be aware that clicking links to third-party websites will take you away from the Crowe Financial Planning website. We are not responsible for the accuracy of information contained within linked sites. |